Metal prices fluctuate because they are set every day on international markets such as the London Metal Exchange (LME), where industrial demand, output from mines and smelters, energy costs, the value of the dollar and political decisions all come together. A company that generates or buys scrap controls none of those variables, but it does control how exposed it is to them: by planning collections, agreeing supply arrangements with a clear price reference and sorting material properly so that each fraction is valued for what it is.
Why do metal prices fluctuate?
Metals are commodities traded worldwide. Their price is not decided by any single producer or buyer, but by the balance between what is produced and what is consumed, with a financial component that amplifies the movements.
A benchmark market that trades every day
Non-ferrous metals such as copper, aluminium, zinc, nickel, lead and tin take their main price reference from the LME, which publishes cash and three-month prices in US dollars per tonne. Any news that affects supply or demand feeds through to those prices within hours. If you want to understand how it works from the inside, we cover it through the BIR’s educational series on the LME.
Supply and demand
Demand is driven by construction, the automotive industry, the electrical industry and packaging, and to a large extent by China, the world’s largest consumer of metals. Electrification has added pressure: grids, renewables and electric vehicles need a great deal of copper and aluminium. On the supply side, a strike at a mine, a smelter closure or an export restriction can cut supply suddenly.
Energy
Producing metal from ore uses a lot of energy, especially in the case of primary aluminium, which is obtained by electrolysis. When electricity becomes more expensive, some plants cut output and the price rises. This is one of the reasons why recycled metal, which needs far less energy, is gaining ground in industry.
Currencies
Because prices are quoted in dollars, a Spanish company sees the price move in euros even when the LME price has not changed. If the euro weakens against the dollar, metal becomes more expensive in euros, and vice versa.
Politics, tariffs and finance
Tariffs and sanctions can change the routes metal takes overnight. The tariffs the United States raised in 2025 on imported steel and aluminium are a good example: they made metal more expensive within the country and altered trade flows across the rest of the world. On top of all this come the movements of investment funds and the level of stocks in LME warehouses, which amplify both rises and falls.
What drives the price of each metal?
Each metal has its own drivers. This table sums up the ones that carry most weight for the metals traded in the recycling sector:
| Metal | Main uses | What usually moves its price |
|---|---|---|
| Copper | Cable, motors, transformers, construction | Electrification, mine output, Chinese demand |
| Aluminium | Transport, construction, packaging | Energy costs, Chinese production, tariffs |
| Steel and ferrous scrap | Construction, automotive, machinery | Construction demand, iron ore, tariffs, international scrap prices |
| Nickel | Stainless steel, batteries | Stainless steel and battery production, supply concentrated in a few countries |
| Zinc | Galvanising steel, zamak | Steel production, construction, mine closures or openings |
| Lead | Starter batteries | Battery demand and recycling volumes |
| Tin | Electronic solder, bronze | Electronics demand and highly concentrated supply |
How do price fluctuations affect scrap?
Non-ferrous scrap is valued on the basis of the LME price, adjusted for the grade, cleanliness, quantity and logistics of each lot. If the LME rises or falls, the value of your copper or aluminium moves in the same direction, though not by the same proportion for every grade. We explain this in detail for copper and for aluminium scrap.
Ferrous scrap follows its own international market, linked to demand from steel mills and the price of steel. In both cases, what the company generating the scrap can control is the same: the quality of what it hands over and how it hands it over.
What can a company that generates scrap do?
Plan collections instead of stockpiling
Holding on to scrap while waiting for a price rise is betting against a market that nobody can reliably predict. Meanwhile, the material takes up space, gets dirty or rusts, and can cause safety and waste storage problems. Collecting regularly spreads the risk: sometimes you sell above the average and sometimes below it.
Agree regular supply with a clear price reference
If you generate volume on a regular basis, a periodic collection agreement with containers on your premises gives both parties predictability. What matters is that the valuation is referenced to a public index, such as the LME, and that you know which characteristics of your material adjust it.
Sort at source
This is the lever that depends most on you. A mixed lot is valued as a mix; separated by metal and grade, each fraction is paid for what it is. Separating copper from brass, extruded aluminium from cast aluminium, or 316 stainless from 304 usually adds more than picking the best moment to sell. The guide to metal alloys explains why.
Ask for transparent valuations
Ask for an explanation of what the valuation is based on: which market reference is used and which characteristics of your material adjust it. With that information you can compare offers on a sound basis and understand why they change.
And a company that buys metal?
Companies that depend on a metal for manufacturing usually combine several tools: supply contracts with prices referenced to the LME, hedging on the futures market to lock in the price of a future purchase today, supplier diversification, and budgets with allowances for price variation on long projects. Recycled metal, available close by and with a smaller energy footprint, is part of that strategy.
How does Alberich work with market prices?
We use the LME as the reference for valuing the non-ferrous metals we buy, so our prices follow its movements. With customers who generate or consume volume on a regular basis, we sign supply agreements with prices referenced to the LME.
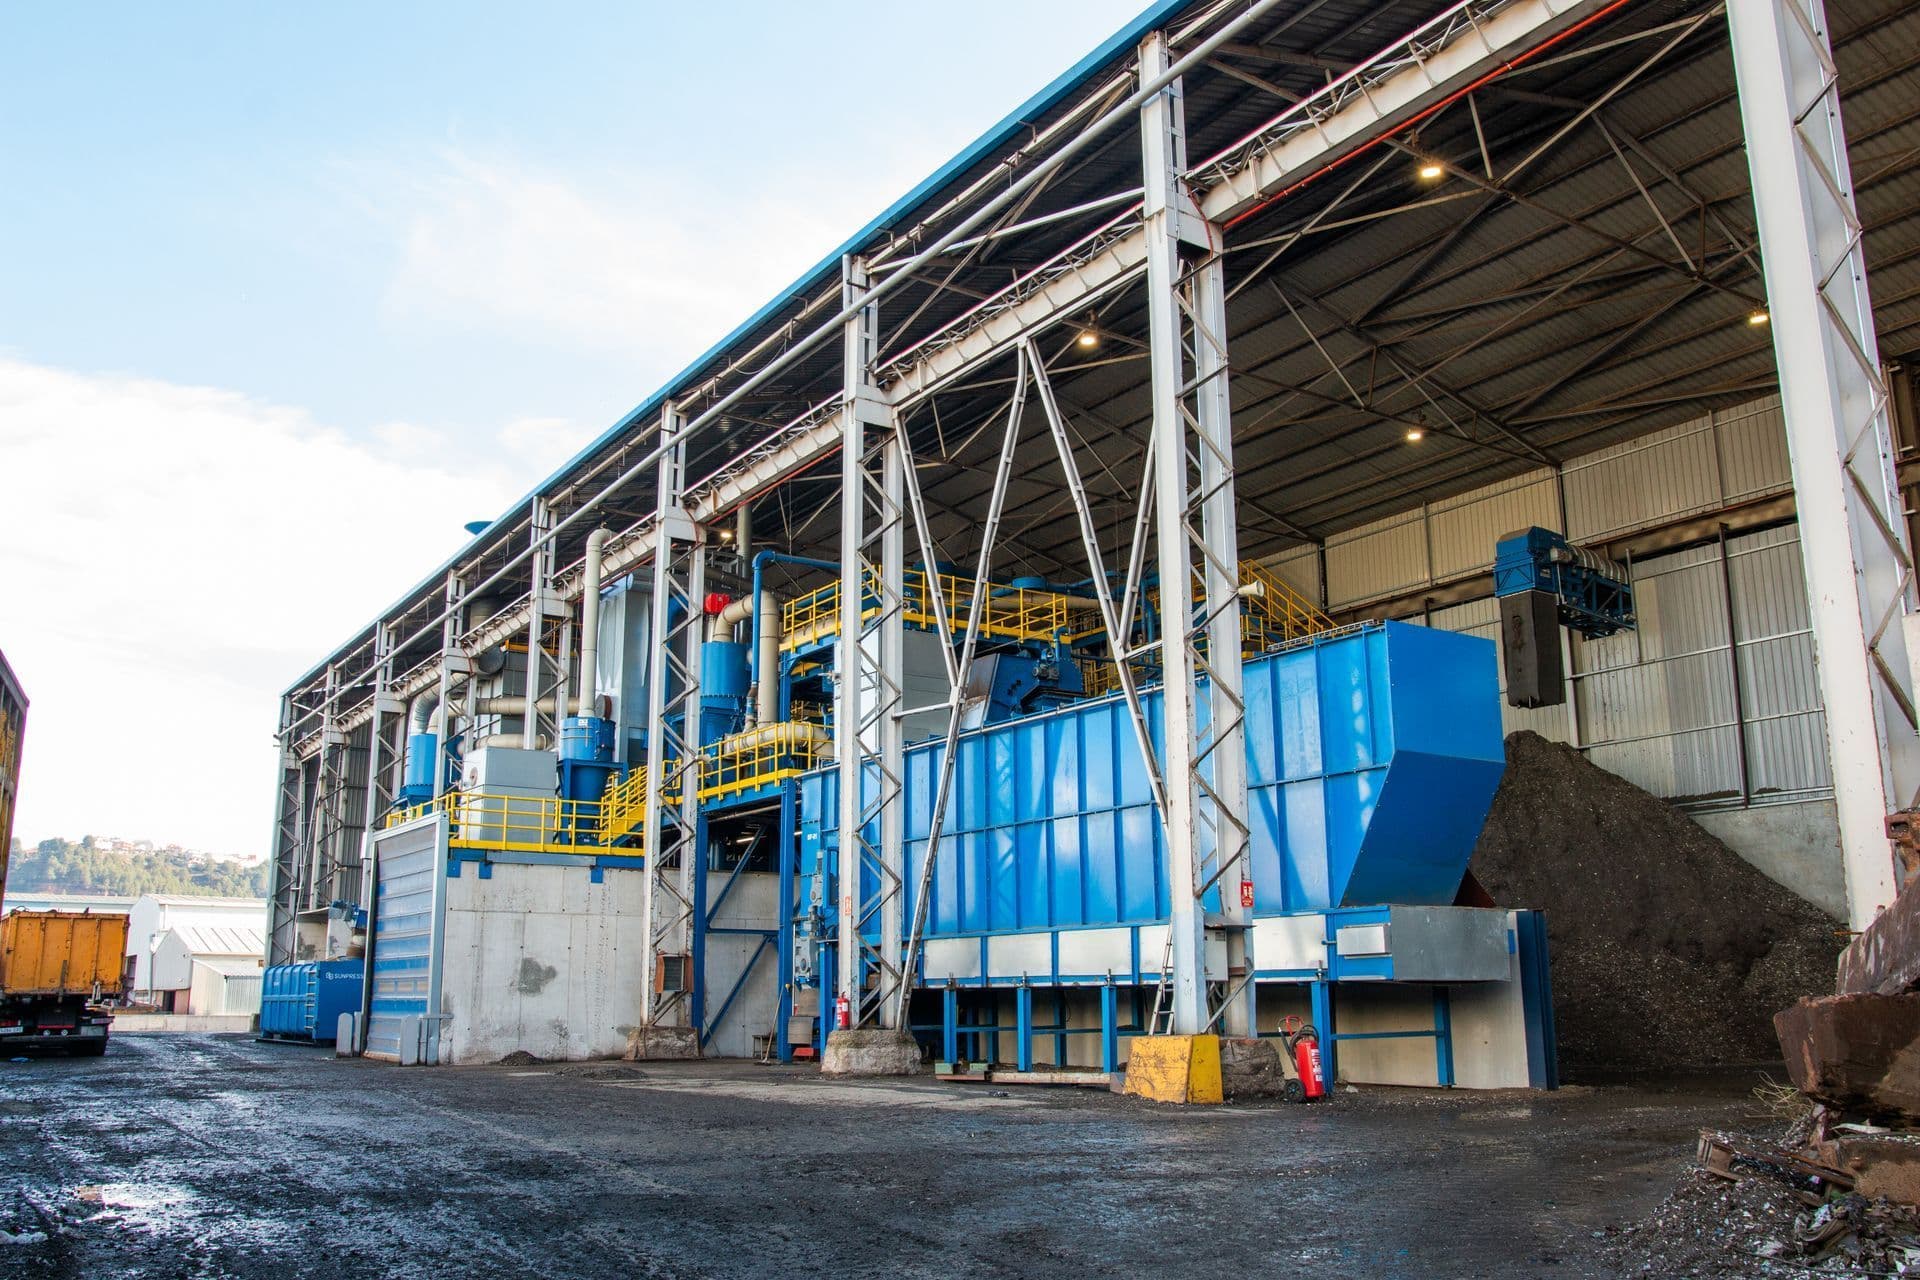
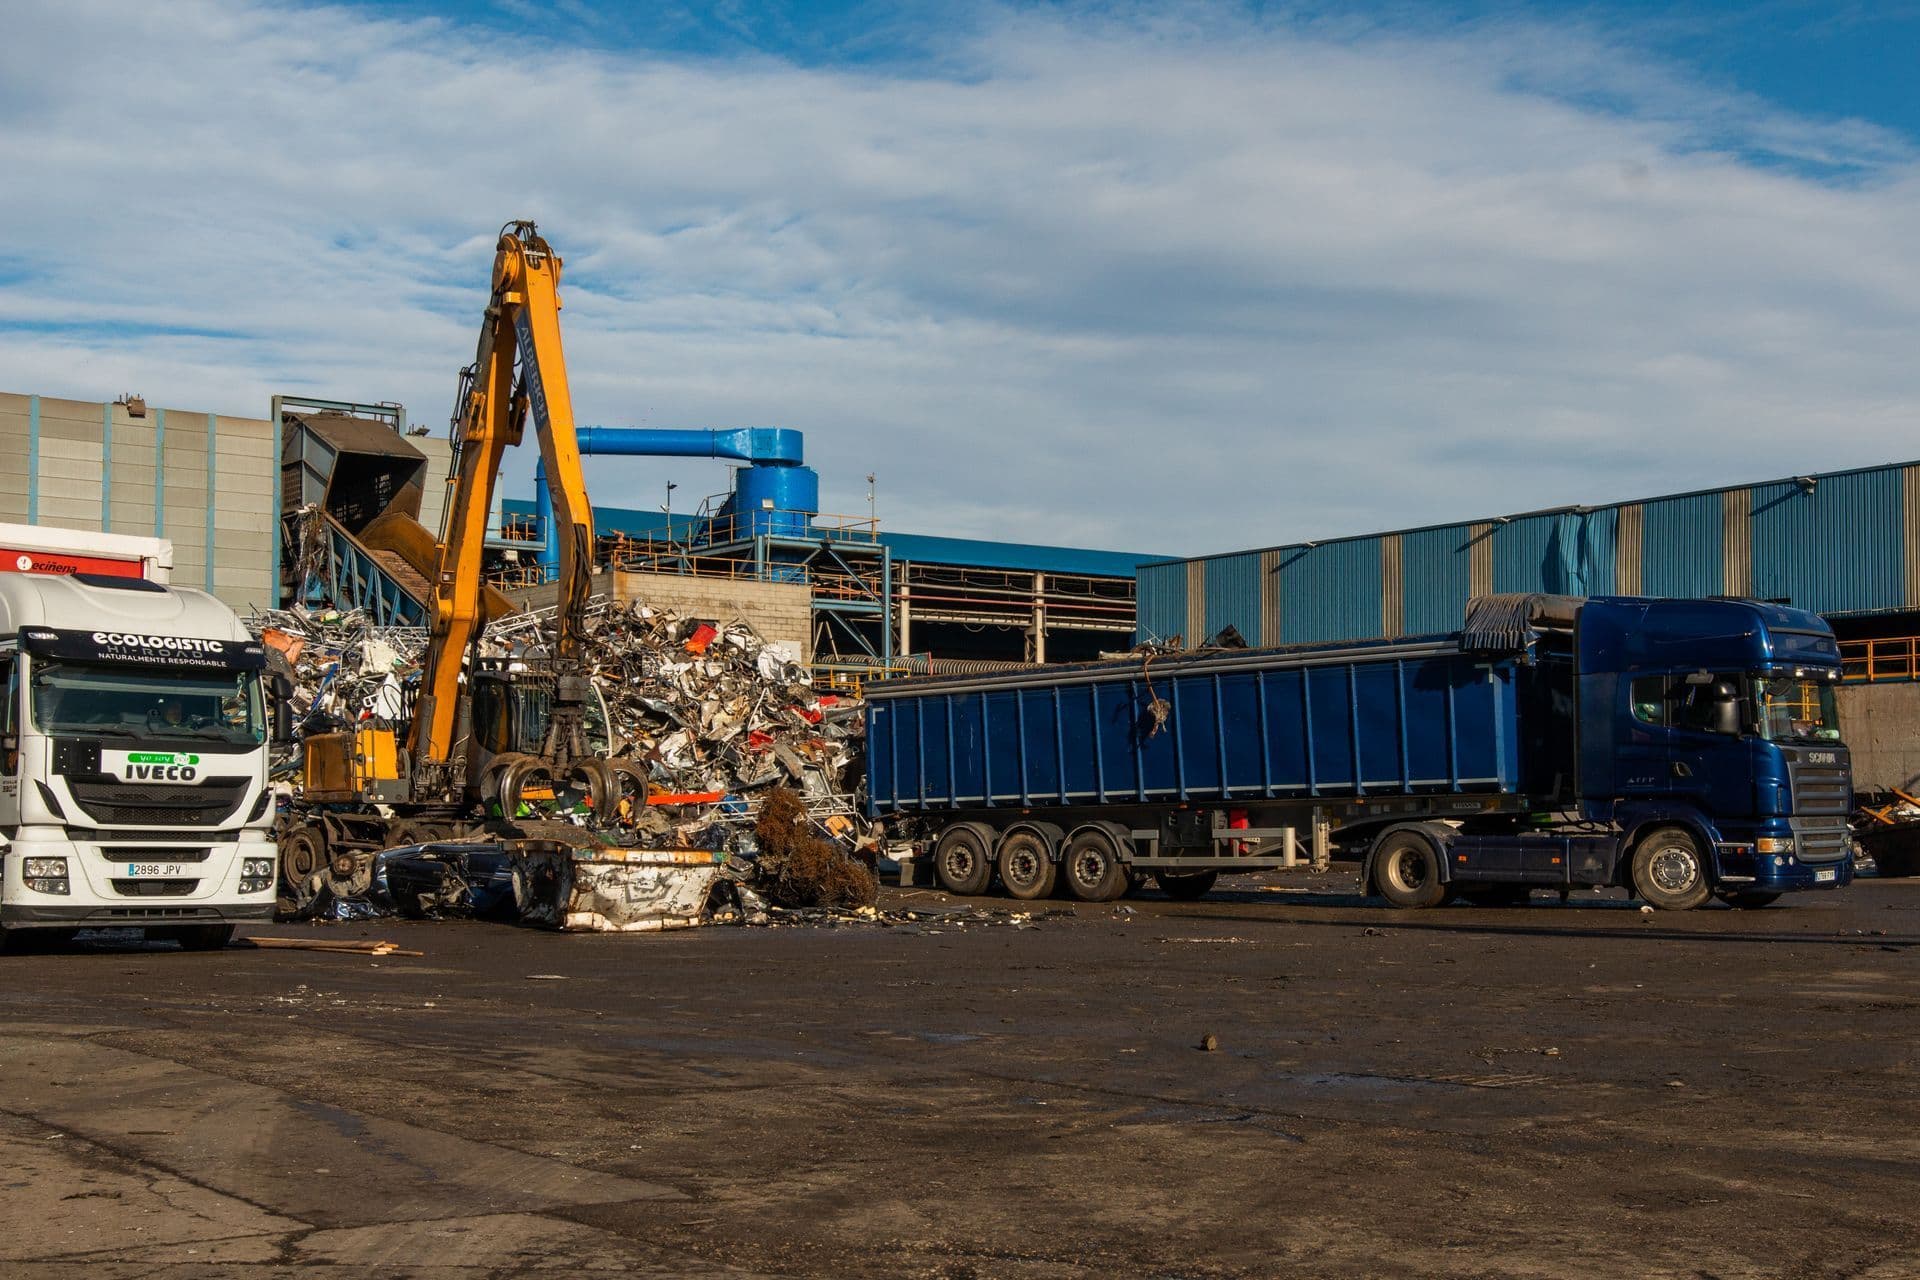
To make sorting at source easy, we leave 1–30 m³ containers at the customer’s premises and collect them with our own fleet, with all the waste documentation. At the plant, more than 300,000 tonnes a year go through our sorting and separation lines. You will find the list of materials in what we buy.
Frequently asked questions
Is it worth holding on to scrap until the price goes up?
Generally, no. Nobody knows when the next peak will come, and while you wait the material takes up space, deteriorates and may end up being worth less. For most companies, collecting regularly and sorting well gives a better result than trying to time the market.
Why doesn’t the price I’m offered match the LME price?
Because the LME quotes refined metal, in dollars per tonne, and scrap still has to be sorted, transported and remelted. The valuation starts from that reference and adjusts it for the grade, cleanliness, quantity and logistics of your lot.
Is ferrous scrap also traded on the LME?
Not in the same way as copper or aluminium. The LME does have steel scrap contracts, but in practice ferrous scrap is valued according to the international scrap market and the price of steel, which depend mainly on demand from steel mills.
Where can I check metal prices?
On the London Metal Exchange website, which publishes its official prices, and through specialist market information services. Bear in mind that those figures are the reference for refined metal, not the price of your scrap.
If you want to review how the metals your company generates are valued, tell us what materials and volumes you have.